Workers' Comp Class Codes for Spray Foam Crews: Why Misclassification Costs You Money
By Josh Cotner
Workers' Comp Class Codes for Spray Foam Crews: Why Misclassification Costs You Money
Here's a scenario we see more often than you'd think: a spray foam contractor renews their workers' comp policy, the rate goes up again, and nobody on their end can explain why. The loss history is clean. The crew hasn't grown. But the bill keeps climbing.
Nine times out of ten, when we pull the policy and look at the classification page, we find the problem in about five minutes. Everyone on the crew — the applicator running the gun, the helper mixing sets and moving hose, the driver hauling the rig between jobs — is coded under one generic construction or insulation classification. Sometimes it's the wrong code entirely for the actual work being done. That's misclassification, and it's one of the most common ways spray foam operations end up overpaying on workers' comp.
The Misclassification Problem
Workers' comp class codes exist to price risk. The code is supposed to reflect what a worker actually does all day, because different jobs carry different injury exposure. The problem is that a lot of carriers and agents don't have a spray foam-specific program, so they default to a generic construction or general insulation code and apply it across the board. It's the path of least resistance for the person writing the policy — it's just not accurate for the person doing the work.
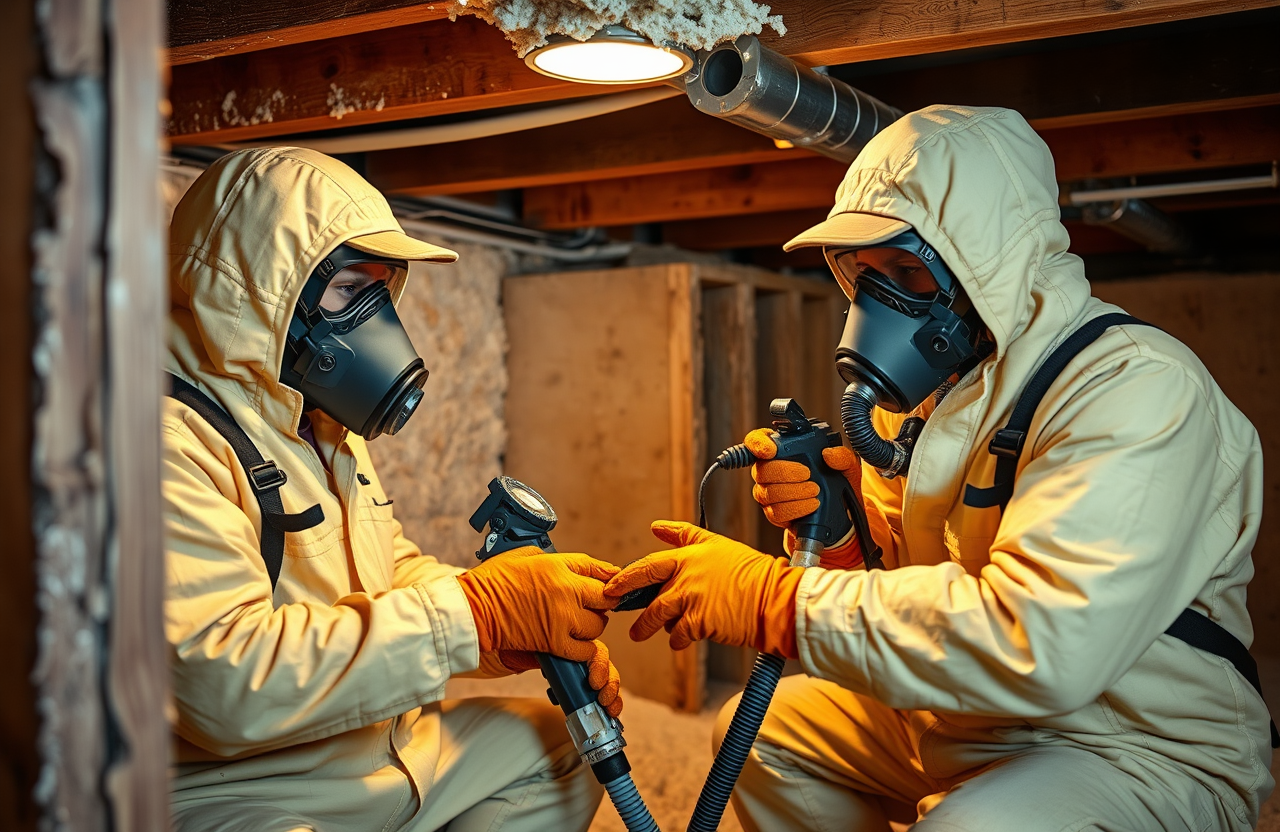
A three-person crew is a good example. Say you've got an applicator in a supplied-air respirator and Tyvek suit running the spray rig eight hours a day, a helper on the ground managing plural-component equipment and material handling, and a driver who splits time between hauling the rig and doing office paperwork. Those are three genuinely different risk profiles. But if the policy has all three coded identically under one generic labor classification, the carrier is pricing the office-adjacent driver at the same hazard level as the guy standing in an overspray cloud — and pricing the applicator at a rate that may not reflect the specialized chemical and equipment exposure of the job either. Either way, something's mispriced, and it's rarely in the contractor's favor once the mod and audit catch up to it.
What a Correct Class-Code Breakdown Looks Like
The fix isn't complicated, but it does take someone actually looking at your crew roster against your payroll records. Applicators — the people physically running spray equipment and doing the installation — typically fall under insulation-installation class codes built for that work. Helpers, drivers, and office or administrative staff are supposed to carry different codes entirely, because their day-to-day exposure doesn't match the applicator's.
When a policy lumps everyone into one code, you're not just risking overpayment — you're also carrying inaccurate records that can complicate an audit down the road. A carrier that later determines your crew was misclassified can adjust premium retroactively, and that's a worse conversation to have after the fact than before renewal. A straightforward class-code review — matching actual job duties and payroll allocation against the codes on your policy — is how this gets caught and corrected. It's one of the first things we look at when a spray foam contractor asks us to compare rates before a renewal.
Isocyanate Exposure: A Distinct Workers' Comp Risk Factor
This is the piece that generic construction or insulation content almost never addresses, and it's worth spending real time on because it's specific to your trade.
Spray polyurethane foam is a two-component system, and one of those components contains isocyanates — a class of chemicals that can cause respiratory sensitization with repeated or improperly protected exposure. That's a fundamentally different injury pathway than a fall, a laceration, or a strain, which is what most generic construction class codes are built around. A code designed for framing crews or general laborers isn't accounting for a chronic respiratory or chemical-sensitization claim, and that mismatch is part of why generic codes so often don't fit spray foam labor well.
From a workers' comp standpoint, this matters in two ways. First, it's a category of claim your policy needs to actually be underwritten to expect — supplied-air respiratory protection, decontamination procedures, and ventilation protocols on the jobsite are all part of how that exposure gets managed, and carriers that understand the trade price around that reality differently than carriers applying a boilerplate code. Second, it reinforces why the applicator role specifically needs its own accurate classification, separate from helpers and drivers who may have materially lower direct exposure depending on how your crew is actually organized on site. This is exactly the kind of hazard we walk through with contractors when we're comparing carriers — some have built spray foam-specific underwriting around this exposure, others are still pricing it as generic insulation work.
The Experience Mod Factor — and Why It's Worth Understanding
Your experience modification factor, or X-mod, is a separate number from your class codes, but it works alongside them. The mod compares your actual claims history to what's expected for a business your size in your industry. A mod under 1.0 means your losses have run better than expected and you get a credit on premium. A mod over 1.0 means the opposite — a surcharge.
Here's why this matters beyond the renewal bill: your mod tells you something about which markets are going to compete hardest for your business. A contractor with a strong mod and clean loss history has leverage to shop that policy across multiple carriers and find the most competitive program. A contractor who doesn't know their own mod — or doesn't know it's being calculated off classifications that were wrong to begin with — is negotiating blind. Combined with an accurate class-code breakdown, your mod is one of the two biggest levers in what you actually pay for coverage.
What You Can Do Now
If you haven't had your current workers' comp classification reviewed against what your crew actually does day to day, that's the place to start — especially if your rate has been climbing without a change in loss history, or if you've never been sure your applicators, helpers, and drivers are coded separately. We compare WC rates across multiple carriers for spray foam applicators, evaluating class codes, experience mod factors, and pricing side by side, so you can see whether your current program actually reflects your operation or whether you're paying for someone else's risk profile. If you're not sure where your policy stands, that review costs you nothing but a conversation.
Need this coverage for your spray foam business?
Get a real quote in about 15 minutes — we shop A-rated specialty contractor markets.